So, you’re curious about how much auto insurance costs in Massachusetts? Well, you’ve come to the right place! Whether you’re a long-time Bay Stater or a newcomer to the region, navigating the nuances of auto insurance can feel as tricky as Boston’s infamous traffic. But fear not, because we’re about to break it all down.
From the factors that determine your rates to the discounts you can snag, we’re diving deep into the world of Massachusetts auto insurance. Buckle up as we explore everything you need to know, with insights that will not only enlighten you but might just save you some serious cash.
Factors Influencing Auto Insurance Costs in Massachusetts
Did you know that the average auto insurance cost in Massachusetts is higher than the national average? If you’re scratching your head wondering why, you’re in the right place. Let’s break down the main factors that drive these costs.
In Massachusetts, auto insurance rates are determined by several key factors: your driving history, the type and age of your vehicle, and even your zip code. Each of these plays a crucial role in calculating your premium. Understanding these can help you find ways to potentially lower your costs.
Driving History: Your Record Matters
Your driving record is like a report card for insurers. If you’re a safe driver with no accidents or violations, you’re likely to pay less. BUT if you’ve had a few fender benders or speeding tickets, brace yourself for higher premiums. Insurers see you as a higher risk, and they charge accordingly.
Pro Tip: Keep a clean driving record for several years, and you’ll see a noticeable drop in your insurance rates.
Impact of Vehicle Type and Age
The type of vehicle you drive can significantly affect your insurance costs. Here’s the deal: sports cars, for example, usually come with higher premiums because they’re designed for speed and more prone to accidents. On the other hand, an older, less flashy car might cost you less to insure. Also, newer cars often have safety features that can lead to discounts on your policy.
Geographic Influence: Where You Live Matters
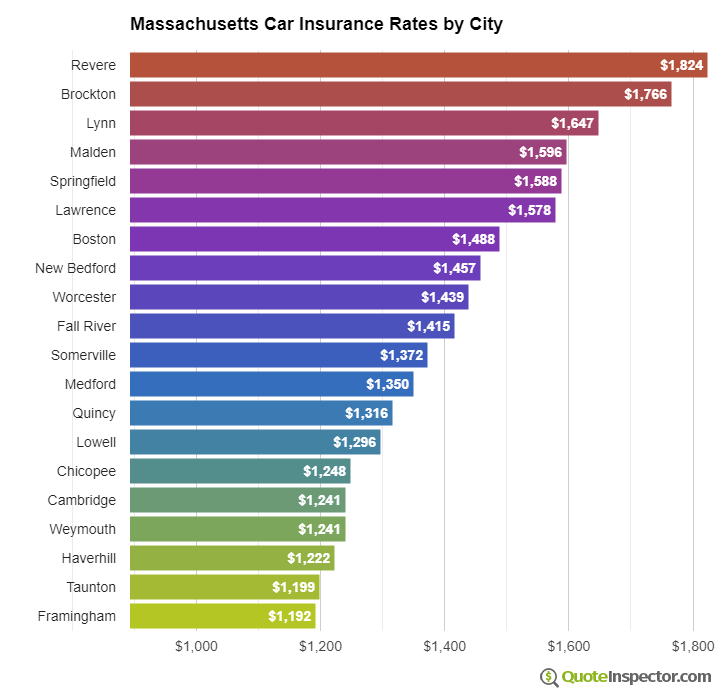
Believe it or not, your zip code can impact how much you pay for auto insurance in Massachusetts. Urban areas like Boston often come with higher rates due to increased traffic and accident risks. Conversely, living in a rural area might give you a break on your premiums.
Here’s a quick look at how your location might influence your rates:
| Location | Insurance Rate Impact |
|---|---|
| Boston | Higher |
| Springfield | Moderate |
| Amherst | Lower |
Typical Auto Insurance Costs in Massachusetts
You want to know how much you’ll need to shell out for auto insurance in Massachusetts, right? I’ve got you covered. Let’s break it down!
Understanding what you’ll pay for auto insurance in Massachusetts can be a game-changer for your budget. Insurance rates vary widely based on several factors, but here’s a look at some average costs you can expect.
Average Costs for Different Coverage Levels
First up, let’s look at the average costs. In Massachusetts, the average cost for minimum coverage is around $600 per year. BUT, if you’re thinking about full coverage, expect that number to jump to about $1,700 annually.
| Coverage Type | Average Annual Cost |
|---|---|
| Minimum Coverage | $600 |
| Full Coverage | $1,700 |
So, why the big difference? Full coverage includes collision and comprehensive insurance, which provides a lot more protection — and as you can see, it impacts your wallet too.
Seasonal Variations in Insurance Pricing
Wondering if you should wait for a better deal? Here is the deal: insurance pricing in Massachusetts doesn’t fluctuate much seasonally. While you might find small discounts from insurers at different times, the impact on your premium is usually negligible.
Some folks think there are better times to buy insurance, but in reality, timing isn’t a major factor. Your rate is more likely to be influenced by your personal driving history and the coverage you choose.
Cost Trends Over the Past Few Years
Now, let’s talk trends. Over the past few years, auto insurance costs in Massachusetts have been on the rise. From 2018 to 2022, the average increase was about 4% per year.
Why the uptick? Updated safety features and more expensive car parts are driving costs up. Plus, with more drivers on the road, insurers are facing more claims.
Pro Tip: Keep your driving record clean to potentially save hundreds on your premiums!
In summary, while rates are increasing, understanding the factors at play and shopping around can help you find a policy that fits your budget.
Legal Requirements for Auto Insurance in Massachusetts

Are you ready to steer through the legal jungle of auto insurance in Massachusetts? Here’s the deal: if you’re driving in the Bay State, you need to be aware of some minimum requirements.
Massachusetts demands that every driver carries auto insurance. This isn’t just a suggestion; it’s a legal requirement. Without it, you could face serious penalties. But what exactly do you need to be covered? Let’s break it down.
Minimum Legal Requirements
Here’s what you’re legally required to have:
- Bodily Injury to Others: $20,000 per person, $40,000 per accident.
- Personal Injury Protection (PIP): $8,000 per person.
- Bodily Injury Caused by an Uninsured Auto: $20,000 per person, $40,000 per accident.
- Damage to Someone Else’s Property: $5,000 per accident.
These are the bare minimums. Driving without meeting these requirements isn’t just risky; it’s illegal!
Penalties for Non-Compliance
Ignoring the law comes with some hefty consequences:
- Fines ranging from $500 to $5,000.
- License suspension.
- Possible jail time, depending on the severity of the offense.
- Increased future insurance premiums.
You don’t want to mess around with these penalties. Trust me, it’s not worth the risk!
No-Fault Insurance Concept
Massachusetts operates under a no-fault insurance system. This means that after an accident, your insurance pays for your damages, no matter who caused the accident. Sounds great, right? But there’s a catch.
Your right to sue is limited unless the damages cross a certain threshold. This is designed to reduce litigation, but it’s crucial to understand your coverage scope.
Optional Coverages to Consider
Just because you meet the minimum doesn’t mean you’re fully protected. Consider these optional coverages:
- Comprehensive Coverage: For damage not involving a collision (e.g., theft, fire).
- Collision Coverage: Covers your car in the event of an accident, regardless of fault.
- Rental Car Reimbursement: Pays for a rental car while yours is being repaired.
- Roadside Assistance: Covers towing and emergency roadside services.
Pro Tip: Opting for higher coverage limits and additional options can save you money and headaches in the long run.
Make sure you’re not just meeting the legal requirements, but also protecting yourself from potential financial pitfalls.
Discounts and Savings Opportunities
Did you know you could slice up to 30% off your auto insurance premium in Massachusetts? It’s true, and it all comes down to leveraging discounts and savings opportunities.
You’ve navigated the cost landscape, and now it’s time to unlock the secrets of lowering your bill. The key is understanding which discounts apply to you and how to qualify for them.
Common Discounts for Massachusetts Drivers
Insurers love rewarding safe and loyal customers. That means you could be eligible for multi-policy discounts if you bundle your auto insurance with home or renters insurance. Not only does this simplify your bills, but it can also save you a tidy sum.
- Good Driver Discount: Keep a clean driving record, and enjoy a reduction on your premium.
- Low Mileage Discount: Driving less could mean paying less.
- Student Discount: Young drivers hitting the books hard might qualify for savings.
Pro Tip: Always ask your provider about discounts you might qualify for, even if they aren’t advertised.
Comparing Bundling Offers
Not all insurance providers are created equal when it comes to bundling offers. Some might offer a 10% discount while others provide up to 25%.
| Insurance Provider | Bundling Discount |
|---|---|
| Provider A | 10% |
| Provider B | 15% |
| Provider C | 25% |
Here is the deal: A little research can lead to big savings. Make sure to compare these offers side-by-side before committing.
Qualifying for Good Driver Discounts
It’s simple: Drive responsibly, and you’ll likely find yourself in line for a good driver discount. But what does “responsibly” mean?
Maintaining a clean driving record with no accidents or moving violations for a specified period, usually three to five years.
That’s really all it takes. You might also need to avoid claims during this period to maximize your savings potential.
Saving with Vehicle Safety Features
Your car might be saving you money in ways you didn’t even realize. Many insurers offer discounts for vehicles equipped with advanced safety features.
Think anti-lock brakes, airbags, and anti-theft systems. These features not only protect you on the road but can also protect your wallet.
Step #1: Check your vehicle for these features. Step #2: Inform your insurer to cash in on those savings.
Process of Obtaining Auto Insurance in Massachusetts
Getting auto insurance in Massachusetts can feel like navigating a maze. But with a clear roadmap, you can streamline the process and ensure you’re fully covered.
Let’s break down exactly how you can get from zero to insured without the usual headaches.
Step-by-Step Guide to Acquiring Auto Insurance
The first step is knowing what you need. Start by listing your coverage requirements based on your vehicle type and driving habits. This helps you narrow down options effectively.
- Assess Your Needs: Consider factors such as your car’s value, potential liabilities, and personal risk tolerance.
- Gather Necessary Documentation: You’ll need your driver’s license, vehicle registration, and any prior insurance policy details.
- Research Providers: Compile a list of reputable insurance companies that offer policies in Massachusetts.
- Request Quotes: Use online tools to compare quotes. This gives you a snapshot of what each provider offers.
- Select and Purchase: Choose a provider that offers the best value for your needs and finalize the purchase.
Documentation Required for Insurance Applications
Documentation is critical when applying for insurance. Without the right papers, you’ll be stuck in the application phase.
You’ll need a valid driver’s license, which proves your ability to drive legally. Also, your vehicle registration is crucial to verify the car you intend to insure. Have your existing insurance policy details on hand if you’re switching providers.
Methods to Compare and Select Insurance Quotes Online
Choosing the right insurance isn’t about picking the cheapest option. It’s about finding the best coverage at a fair price. Here’s how you can do that efficiently:
Use online comparison tools to see multiple quotes side by side. Each tool provides a different perspective on premiums and coverage levels.
Pro Tip: “Don’t just compare prices. Look at what’s included in the coverage.”
With these tools, you can filter by coverage type and limits to see what best suits your financial and protection needs.
The Role of Insurance Agents in Facilitating the Process
Insurance agents can be your best ally or just another line on your to-do list. Here’s how to make them work for you:
Agents have inside knowledge of the insurance market and can provide tailored recommendations. They can negotiate better rates and help you understand the fine print.
However, it’s crucial to do your homework first. Know what you want before you consult an agent to ensure they’re genuinely enhancing your decision-making process.
Impact of State Legislation on Auto Insurance
Did you know that recent legislative changes can drastically alter your auto insurance premiums in Massachusetts? State laws are constantly evolving, and they have a direct impact on how much you’ll pay for coverage.
Here’s the deal: state-mandated adjustments require insurance companies to tweak their offerings, which can lead to both increased costs and new savings opportunities. Understanding these changes is crucial for making informed decisions about your policy.
Recent Legislative Changes Affecting Auto Insurance
In the past year, Massachusetts has passed several laws aimed at enhancing consumer protection and ensuring fair pricing. These laws mandate insurance providers to offer more transparent pricing and better coverage options. However, they’ve also introduced stricter penalties for uninsured drivers, which can indirectly affect your premium.
Implications of State-Mandated Coverage Adjustments
State-mandated adjustments mean that your insurance must now include certain coverages that might have been optional before. For instance, personal injury protection (PIP) limits have been revised, adding a layer of security for drivers. BUT, this can also lead to increased premiums if you’re not careful about your coverage choices.
How New Laws Impact Premium Calculations
When state legislation changes, insurers must recalibrate their premium calculations to comply with new rules. This often involves complex algorithms that take into account risk factors and coverage requirements. Industry experts note that while premiums may rise for some, others could benefit from lower rates due to improved risk pooling.
Feedback from Industry Experts on Recent Policy Changes
Insurance industry leaders generally support these legislative updates, stating they lead to fairer pricing structures and better consumer protection. However, they also caution policyholders to stay informed about these changes to avoid unexpected surprises in their billing statements.
Pro Tip: Keep an eye on legislative updates and review your policy annually to ensure you’re not overpaying or missing out on potential savings.
Closure
As you can see, understanding how much auto insurance costs in Massachusetts involves a blend of factors, from your driving history to where you park your ride at night. With this knowledge, you’re now equipped to make savvy decisions that could lead to substantial savings. Remember, the more informed you are, the smoother the ride will be when it comes to your insurance journey.
Q&A
What factors influence auto insurance costs in Massachusetts?
Key factors include driving history, vehicle type, age, and geographic location.
How does driving history affect insurance premiums?
A clean driving record can lead to lower rates, while accidents or violations may increase premiums.
What are the average auto insurance costs in Massachusetts?
Average costs vary, but estimates suggest around $1,000 for minimum coverage and $2,500 for full coverage annually.
Are there legal requirements for auto insurance in Massachusetts?
Yes, drivers must carry minimum liability coverage and personal injury protection (PIP).
Can I get discounts on my auto insurance in Massachusetts?
Yes, common discounts include those for good drivers, bundling policies, and having safety features in your vehicle.
